On 28 October 2026 execution registrar Shirley Gideon approved the sale of the debtor's car in Mizrahi Tefahot Leasing's vehicle-pledge file. The decision named the buyer, a car dealer, and next to his name an ID number. The number was not his. It belongs to his daughter, who took no part in the auction and did not sign the sale agreement.
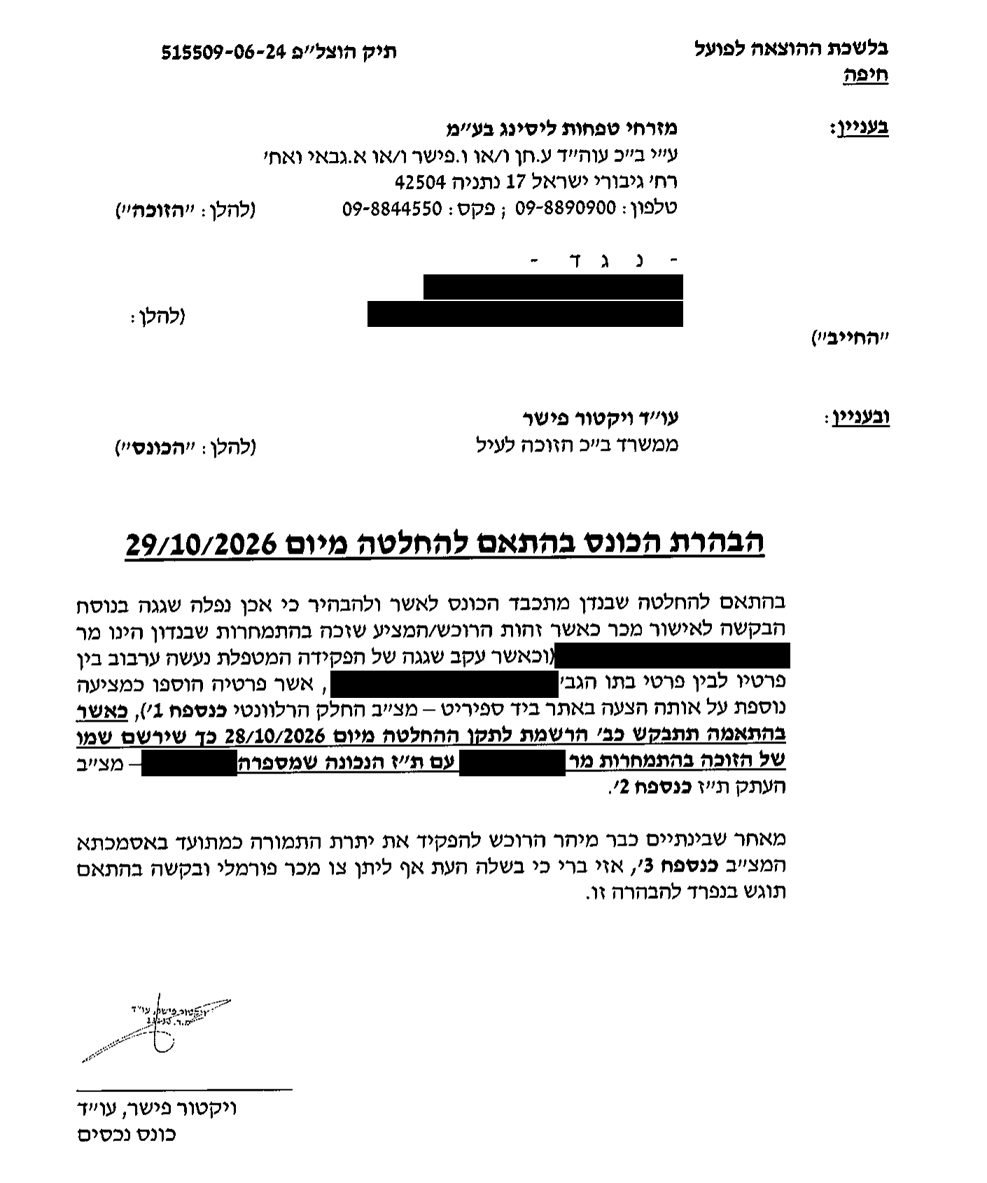
On 2 November 2026 the court-appointed receiver, attorney Victor Fisher, wrote that "an error occurred", "due to an error by the handling clerk". The same day a corrected decision was issued, one that "replaces and cancels" the previous decision. It too states that the sale is approved "in the absence of an objection by the debtor".
We published the start of this story in the dealer, the daughter and the affidavit. This is what happened next.
In brief
- 11.10.2026: an online auction on the Bidspirit platform. A car dealer won with a bid of 73,500 shekels.
- 21.10.2026: the receiver filed a request to approve the sale, giving, next to the dealer's name, his daughter's ID number. His affidavit that the details "were checked" was attached.
- 28.10.2026: the registrar approved the sale "in the absence of an objection by the debtor". The same day the debtor filed an urgent request for a stay and cancellation.
- 29.10.2026: the registrar ordered the receiver to clarify whose number it was and to attach a copy of the buyer's identity card, by 2.11.2026.
- 1.11.2026: the balance of the price, 66,150 shekels, was transferred to a Bank Leumi account in attorney Fisher's name.
- 2.11.2026: the receiver filed a clarification and attached a driving licence. A corrected decision was issued the same day.
The decision of 28 October 2026
This is the full text, without the details of the debtor, the buyer and the daughter:
"Before me is a request for the sale of vehicle licence no. 35410602. An appraisal, copies of the publication (newspaper and 'Bidspirit') and the auction record were attached. An updated vehicle licence and a liens and attachments report were filed. A redemption letter was delivered to the debtor on 18.10.2026. A copy of the delivery confirmation and a process server's affidavit were attached.
1. For the reasons in the request and in the absence of an objection by the debtor, I approve the sale of a Honda vehicle, licence no. 35410602, to [buyer's name], ID [the daughter's ID number], for the sum of 73,500 shekels.
2. The receiver's fee at a rate of 6% + VAT of the sale price, plus the stage A fee in the file.
3. The full price shall be deposited in the execution file (without the VAT component, insofar as it applies); the receiver shall file a financial report and state whether third-party rights exist, and if so, their status regarding distribution of the proceeds (a liens and attachments report must be attached).
4. A formal order will be signed after receipt of the full price and filing of the report."
According to the Execution Office system, the request was filed on 28.10.2026 and approved the same day.
The urgent request and the decision of 29 October
On 28.10.2026 the debtor asked to stay the signing of the order and cancel the approval. He argued that the sale had been approved on a request giving the ID number of a third party, "without her name being stated and without bringing to the registrar's attention the material fact that the car is sought to be registered in the name of a third party, who did not take part in the auction, did not win it and did not sign the sale agreement". He also argued that the auction summons and the redemption letter were never delivered to him and that his signature on the delivery confirmation was forged.
The next day the registrar decided. This is the full decision, without the buyer's surname:
"I have reviewed the debtor's request. The sale of the vehicle in question was approved to [buyer's name]. The receiver shall clarify whether the ID number given in the request for approval of sale is the ID number of Mr [surname]. The receiver shall support his request with a copy of the buyer's identity card. The receiver's clarification, as required above, shall be filed by 02.11.2026. I approve filing the clarification under the urgent procedure.
The debtor's claims about irregularity of the delivery confirmations were not properly substantiated. The debtor did not lay a foundation showing defects in the delivery confirmations that would justify cancelling the sale approval. Nor was a foundation laid that the deliveries were not made to him. There is a presumption of delivery that has not been rebutted.
The sale approval was given by this panel after the set redemption period had passed, when the debtor himself did not seek to exercise the right of redemption and did not deposit the sale price in the file or with the receiver.
I found in the reasons of the request before me no legal grounds for staying the proceedings, particularly as no request for a formal order transferring rights in the vehicle has yet been filed.
The secretariat shall inform the receiver of this decision by telephone and make a note in the file."
The receiver's clarification of 2 November
This is the full text of the clarification, without names and ID numbers:
"Receiver's clarification pursuant to the decision of 29/10/2026
Pursuant to the decision in question, the receiver respectfully confirms and clarifies that an error did occur in the wording of the request for approval of sale, as the identity of the buyer/bidder who won the auction in question is Mr [buyer's name], ID [his number] (and since, due to an error by the handling clerk, his details were mixed up with the details of his daughter Ms [daughter's name], ID [her number], whose details were added as an additional bidder on the same bid on the Bid Spirit site - the relevant part attached as Annex 1), whereupon the honourable registrar will be asked to correct the decision of 28/10/2026 so that the name of the auction winner Mr [buyer's name] is recorded, with the correct ID number [number] - a copy of the ID attached as Annex 2.
Since in the meantime the buyer has already hurried to deposit the balance of the price, as documented in the reference attached as Annex 3, it is clear that the time has come to also grant a formal sale order, and a request accordingly will be filed separately from this clarification."
The clarification is signed "Victor Fisher, Adv., receiver". It was attached to a "request for approval of sale" form dated 2.11.2026, in which the sections "publication and auction", "appraisal", "redemption notice", "additional documents" and "nature of the request" were left blank.
The corrected decision, the same day
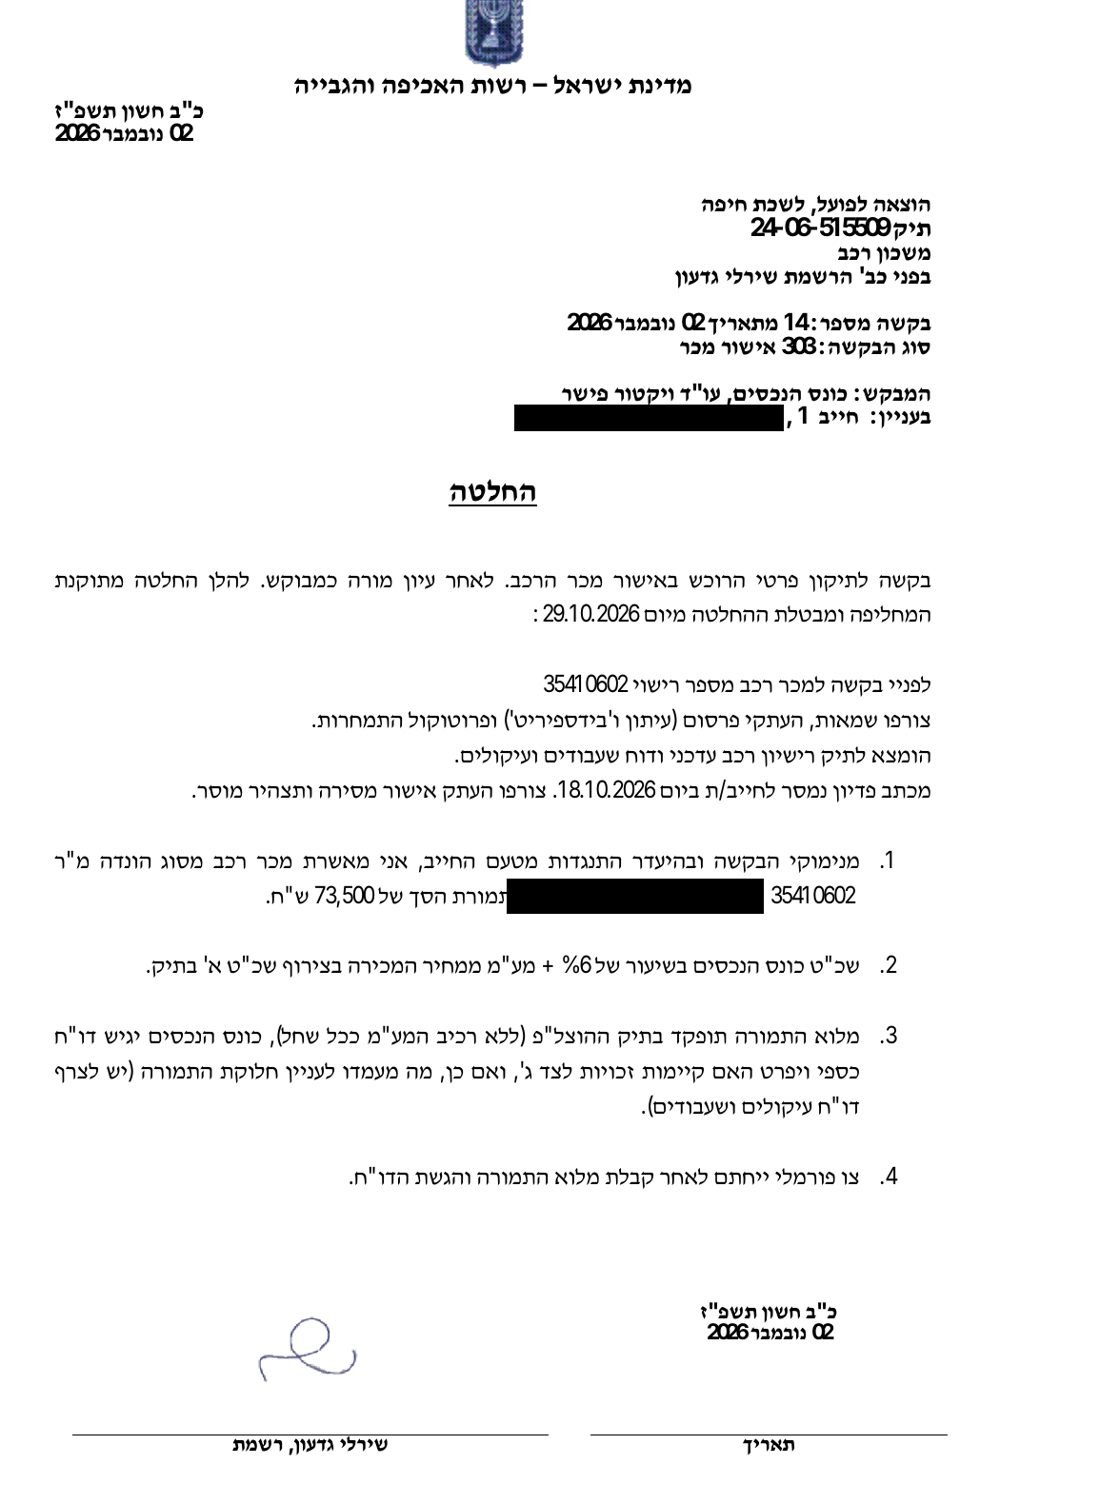
"Request to correct the buyer's details in the approval of sale of the vehicle. Having reviewed it, I order as requested. Below is a corrected decision which replaces and cancels the decision of 29.10.2026.
Before me is a request for the sale of vehicle licence no. 35410602. An appraisal, copies of the publication (newspaper and 'Bidspirit') and the auction record were attached. An updated vehicle licence and a liens and attachments report were filed. A redemption letter was delivered to the debtor on 18.10.2026. A copy of the delivery confirmation and a process server's affidavit were attached.
1. For the reasons in the request and in the absence of an objection by the debtor, I approve the sale of a Honda vehicle, licence no. 35410602, to [buyer's name], ID [his number], for the sum of 73,500 shekels.
2. The receiver's fee at a rate of 6% + VAT of the sale price, plus the stage A fee in the file.
3. The full price shall be deposited in the execution file (without the VAT component, insofar as it applies); the receiver shall file a financial report and state whether third-party rights exist, and if so, their status regarding distribution of the proceeds (a liens and attachments report must be attached).
4. A formal order will be signed after receipt of the full price and filing of the report."
Given on 2.11.2026 by registrar Shirley Gideon, Haifa Execution Office, file 515509-06-24.
What was corrected, and what was not
"An error by the clerk". On 21.10.2026 attorney Fisher signed an affidavit, under warning to tell the truth, that "all the details set out in the attached report were checked and to the best of my knowledge and understanding are correct". The daughter's ID number appears in the request three times. The clarification moves the responsibility to a clerk, but the affidavit is the receiver's.
"An additional bidder on the same bid". According to the clarification, the daughter's details "were added as an additional bidder" on the winning bid. The receiver's own office published next to the auction: "No change of winner's name after winning the tender!". The sale agreement was signed only with the dealer. The clarification does not say who added the daughter, when, why, or why the registrar was not told in the request of 21.10.
Identity card or licence. The decision of 29.10 required "a copy of the buyer's identity card". The clarification calls Annex 2 "a copy of the ID". The document attached as Annex 2 is a driving licence.
"Replaces and cancels the decision of 29.10.2026". The decision of 29.10 is the one that required a clarification and an identity card. The corrected decision replaces it, and restores the wording of 28.10 with a different ID number.
"In the absence of an objection". Between 28.10 and 2.11 the file contained the debtor's urgent request to cancel the sale approval, which the registrar herself decided on 29.10. The corrected decision was issued the same day the clarification was filed, without the debtor being asked to respond. And it states, again, "in the absence of an objection by the debtor".
Where the money is
Paragraph 3 of both decisions says: "The full price shall be deposited in the execution file". According to Annex 3 to the clarification, on 1.11.2026 66,150 shekels were transferred to a Bank Leumi current account described in the reference as "the account of attorney Victor Fisher". That is the account named in clause 2 of the sale agreement.
66,150 is 90% of 73,500. Under the sale agreement, 10% (7,350 shekels) was to be paid within 48 hours of winning. No reference for that payment was attached to the clarification. The clarification presents the transfer to the receiver's account as "depositing the balance of the price" and asks, on that basis, for a formal sale order. The decision itself says the order will be signed "after receipt of the full price" in the file.
The VAT question: we leave it to the reader
Clause 1 of the sale agreement says: "For the vehicle the buyer shall pay the receiver the sum of 73,500 shekels including VAT". The registrar's decision says: "The full price shall be deposited in the execution file (without the VAT component, insofar as it applies)". The buyer is registered with the Israel Tax Authority as a dealer in used motor vehicles. The debtor is also a registered VAT dealer.
Section 18 of the Value Added Tax Law, 5736-1975, lists a receiver among those who sell a dealer's asset "in place of the dealer", and provides: "the tax shall be paid ... out of the consideration ... before it is transferred for any other purpose, and the tax shall not be regarded as part of the consideration".
At 18%, the VAT component inside 73,500 shekels is 11,211.86 shekels, and the price without it is 62,288.14 shekels. The decision sets the receiver's fee at "6% + VAT of the sale price". From 73,500 that is 5,203.80 shekels. From 62,288.14 it is 4,410.00 shekels.
We do not decide this here. The questions are open:
- Does VAT apply to the sale, and who reports and pays it?
- Will a tax invoice be issued to the dealer who bought the car, and in whose name?
- Where is the VAT component now: in the file, in the receiver's account, or on its way to the Tax Authority?
- Is the 6% fee computed on the price with VAT or without it?
The receiver's good faith is binding
A receiver in Israeli enforcement proceedings is not just another lawyer for the creditor. The registrar appoints him, and he acts on the registrar's instructions. He sells property that is not his, belonging to a debtor who is not his client. That is why he owes duties of trust, fairness and good faith to everyone concerned, including the debtor. The duty of candour to the registrar is part of it: to tell her who is really buying, in whose name the car is to be registered, and where the money is.
The ID error was not caught by the receiver's checks. It was caught because the debtor filed a request. And even after it was caught, the decision that followed records that the debtor did not object.
Questions for the receiver, attorney Victor Fisher
- Who added the daughter's details to the winning bid on Bidspirit, when, and at whose request?
- If the daughter was "an additional bidder on the same bid", why was the registrar not told in the request of 21.10.2026?
- What did you check before declaring that the details "were checked"?
- Why was a driving licence attached when the registrar required a copy of an identity card?
- Why was the balance of the price transferred to an account in your name rather than deposited in the file, and where is the reference for the 7,350-shekel payment?
- Will a tax invoice be issued to the buyer, and who will pay the VAT?
This article is based on the decisions of registrar Shirley Gideon of 28.10.2026, 29.10.2026 and 2.11.2026 in file 515509-06-24 (Haifa Execution Office); the debtor's urgent request of 28.10.2026; the receiver's request for approval of sale of 21.10.2026 and its annexes (affidavit, sale agreement, auction record); the receiver's clarification of 2.11.2026 and its annexes; and section 18 of the Value Added Tax Law. Quotations are our translation from Hebrew. The names of the buyer and his daughter, ID numbers, addresses and the debtor's details have been omitted. Claims attributed to the debtor are his version and remain to be decided. The calculations are ours, based on the amounts in the documents. This article was written and edited with the assistance of artificial intelligence. A response from the receiver and the creditor will be published if received.